Audit-Ready Screening Data for Banks
Today’s banks are navigating a high-stakes environment — rising financial crime, expanding regulations, and pressure to deliver frictionless customer experiences. Whether you’re a global institution, regional or mid-sized bank, or digital-first challenger, compliance is no longer a back-office function — it’s central to protecting your customers and your brand.
Vital4 delivers intelligent, scalable compliance solutions that help banks stay ahead of evolving risk — without slowing down innovation. Our platform supports AML compliance and risk mitigation, with sanctions, PEP, Adverse Media screening, and continuous monitoring through automation, AI, and global data coverage.
Banks are examined on outcomes, not activity. Regulators are shifting from counting alerts reviewed to asking whether a program actually detects risk, and examiners expect to see where every screening result came from. Vital4 gives your team direct-source data that traces each result to its original publisher, a logged history of every search and decision, and fewer false positives to work through, so effectiveness is something you can show, not just assert.
Deploy through an API, batch files, or a browser-based SaaS platform with minimal IT lift, so screening sits alongside your existing onboarding, core banking, and case management systems.
If you sponsor fintech programs, you remain responsible for the compliance of the programs you support. Vital4’s screening and ongoing monitoring can be applied to program managers, fintech partners, and their end customers through the same API or batch process.
Evaluating AML software for your bank? See how Vital4 and five other platforms compare on data sourcing, update speed, false-positive handling, auditability, and pricing transparency. Compare the best AML software platforms. →
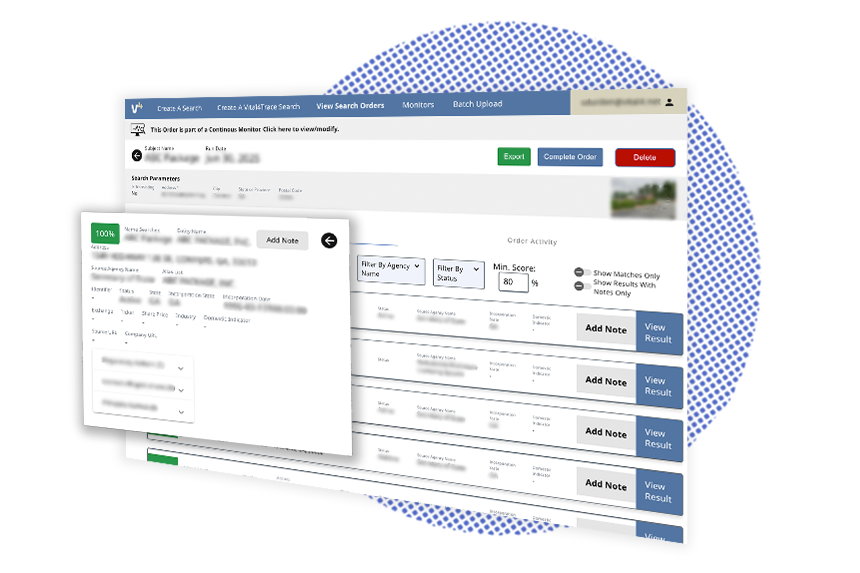
Identify high-risk customers, beneficial owners, and counterparties early, and keep your customer due diligence and OFAC screening aligned with changing BSA/AML expectations, with a logged record you can show examiners.
Continuously screen customers, beneficial owners, and counterparties against sanctions, PEPs, and adverse media, so a relationship that turns high-risk is flagged before it becomes a loss or an exam finding.
Run sanctions, PEP, and adverse media checks at account opening and at each periodic review using real-time data, with Smart Monitoring flagging real changes in between, so reviews follow actual changes in risk rather than the calendar.
Vital4 Solutions
Politically exposed persons hold high-level government roles, directly or through family and close associates, and banks apply risk-based enhanced due diligence to them. Vital4’s PEP data is built in-house, with relationship mapping for relatives and close connections, and flexible pricing with no per-alias fees.
Vital4 Politically Exposed PersonsMedia coverage often flags laundering, fraud, trafficking, and terrorism-financing risk before a customer appears on any sanctions list. Vital4’s patented Contextualized Entity Extraction reads the context around a name, delivering up to 100% fewer false positives on adverse media screening, so analysts review real hits, not name coincidences.
Vital4 Adverse MediaBanks screen customers, beneficial owners, and counterparties against OFAC and other government-published lists, and global watchlists change fast, including delistings. Vital4 collects every government-published watchlist globally directly from the source, so results trace back to the original list.
Vital4 Watchlists & SanctionsEnhanced due diligence on higher-risk customers usually means analysts searching many sources and saving screenshots for the audit file. Vital4Search Due Diligence runs the searches at the same time and returns structured, audit-ready reports your team can attach to the customer file.
Vital4 Search – Due DiligenceDon’t wait for the next periodic review. Event-driven continuous monitoring alerts only when a sanctions, adverse media, or PEP record is new or meaningfully changed, so analysts work real changes, not repeat hits. It runs from the cloud-based interface of Vital4Search.
Stay compliant and reduce long-term reputational risk.
Vital4 Smart MonitoringIndustry Intel from Vital4

FinCEN’s proposed BSA overhaul replaces “check the box” with “prove it works.” What that means for every compliance program in the country.

Federal regulators just codified the end of “reputation risk” as a supervisory tool. The subjective shortcut that drove years of de-risking is gone — and what has to replace it is evidence.

FinCEN’s effectiveness standard is coming. Here is the sequenced roadmap from comment period to exam-ready — and where modern compliance infrastructure fits at every phase.
In the United States, the Bank Secrecy Act is the foundation. Banks need a written AML program with internal controls, a designated BSA officer, independent testing, and staff training, along with a customer identification program, customer due diligence (including beneficial ownership for legal entity customers), suspicious activity and currency transaction reporting, recordkeeping, and OFAC sanctions compliance. Vital4 supplies the sanctions, PEP, adverse media, and ongoing-monitoring data that support the screening and due diligence parts of that program.
Yes. Screening isn’t limited to onboarding, because sanctions lists, PEP status, and media coverage keep changing after an account is opened. Banks rescreen existing customers on a schedule or continuously. Event-driven monitoring, such as Vital4 Smart Monitoring, alerts only on new or meaningfully changed records, so analysts review changes instead of re-reviewing every customer.
Banks typically combine customer screening against sanctions, PEP, and adverse media data, transaction monitoring for unusual activity, and investigation and reporting workflows. Vital4 provides the customer-screening and ongoing-monitoring layer, built on direct-source data with source-level traceability; transaction monitoring and case management come from other systems in the bank’s stack.
Banks should weigh direct-source data and fast list updates, how well the platform reduces false positives, a complete audit trail with source-level traceability, flexible deployment through an API, batch files, or a SaaS platform with minimal IT lift, coverage of sanctions, PEP, and adverse media, and a pricing model that matches how you consume the data, without forced multi-year terms or per-alias billing. Most banks pair screening data with transaction monitoring and case management. Vital4’s comparison of six AML platforms evaluates providers on these criteria.